Most people only think about a roof insurance claim report after a storm. That's one trigger, but it's not the only one, and treating it as a storm-only document is why a lot of homeowners find out what one actually involves at the worst possible time, mid-dispute with an insurer, or mid-settlement on a house they're about to buy.
Here's what a roof insurance claim report actually contains, how it's different from a standard roof inspection, and the situations beyond storm damage where you need one.
What a Roof Insurance Claim Report Actually Is
It's a formal written document, prepared by a licensed roof plumber, that gives your insurer independent, professional evidence of your roof's condition. Unlike a verbal opinion or a quick look from ground level, it's built to be submitted directly as part of a claim, insurers generally won't process a roof-related claim without one.
What's Included in the Report
A proper report from a licensed professional covers:
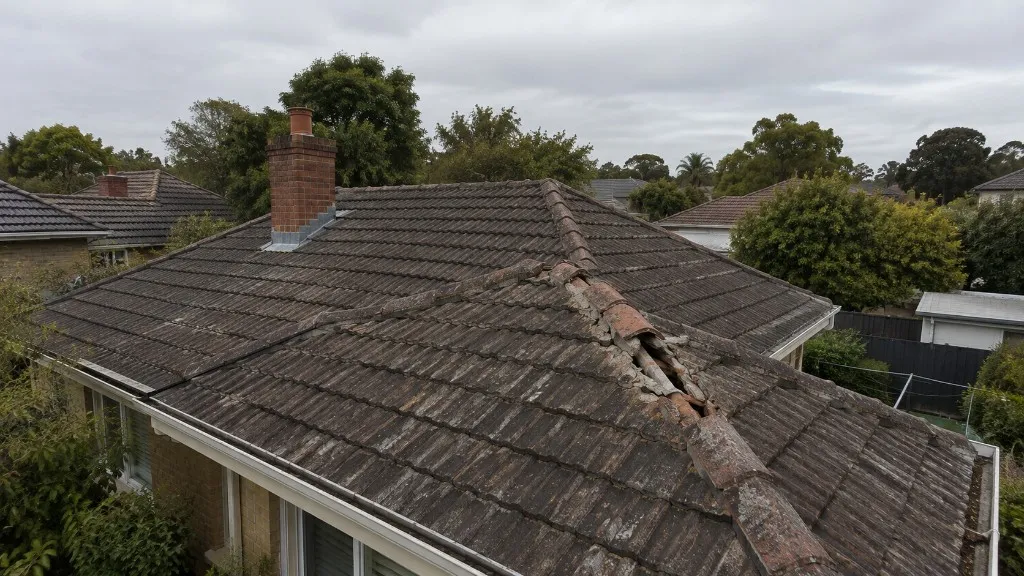
- Photographic evidence of the damage or condition, taken from the roof itself where it's safe to access, not just ground level
- Cause assessment, distinguishing storm or weather damage from general age-related wear, since insurers treat these very differently
- Recommended scope of work, what actually needs repairing or replacing
- Cost estimate for the recommended works, so the insurer has a figure to assess the claim against
This is a different document to a casual inspection. It's written to withstand an insurer's scrutiny, and to hold up if the claim is disputed.
How It's Different From a Standard Roof Inspection
A standard roof inspection is for you, it tells you what's happening on your roof and what it'll cost to fix. An insurance claim report is for your insurer. It's formatted, evidenced, and worded to meet what an insurance company needs to approve or dispute a claim, which is a different job even when the roof plumber is up there doing largely the same physical inspection.
If you're not dealing with an insurer, a standard inspection is the right call, see our guide on when to book a roof inspection for the general timing.
When You Actually Need One
Storm damage is the most common trigger, but it's far from the only one:
- After a storm or hail event, to support an active claim. See our full guide on what to do first after storm damage.
- Buying or selling a property, where a roof report gives buyers, sellers, or their conveyancer independent evidence of the roof's condition before settlement.
- Disputing an insurer's assessment, if your insurer's own assessor has undervalued the damage or attributed it to wear rather than a covered event, an independent report gives you something to push back with.
- General age-related deterioration, where you want documented evidence of a roof's condition for your own records or for a landlord/body corporate requirement.
What It Costs and How Long It Takes
A written roof insurance claim report in Melbourne typically runs $250 to $450, depending on roof size and access, and most reports are turned around within one to two business days of the inspection. If there's active water ingress, ask about priority inspection, most licensed roof plumbers, Cascone included, will move a genuine emergency ahead of the queue.
Book an inspection and report directly, or call for a faster response if the damage is urgent.